
Key Focus This Week:
This Week’s Focus: Fed Policy Path, Global PMI and Canadian Consumer Spending
Global financial markets remained relatively volatile this week, with investors focused on the artificial intelligence boom, rising long-term interest rates, fluctuations in energy prices, and geopolitical developments.
U.S. equities started the week on a strong note, led primarily by technology and semiconductor stocks. On September 21, the Nasdaq Composite rose 2.26%, the S&P 500 gained 1.49%, and the Dow Jones Industrial Average increased 0.71%. The Philadelphia Semiconductor Index (SOX) gained 4.3% that day, while AMD rose approximately 10% and its market capitalization surpassed US$1 trillion for the first time. Intel and Arm Holdings gained approximately 12% and 17%, respectively.
Meta was also a major focus within the technology sector this week. Early user growth for the company’s AI assistant, Muse, continued to attract investor attention, while Meta Connect further showcased the integration of Muse with AI glasses and other hardware products. Meta shares gained approximately 13% for the week.
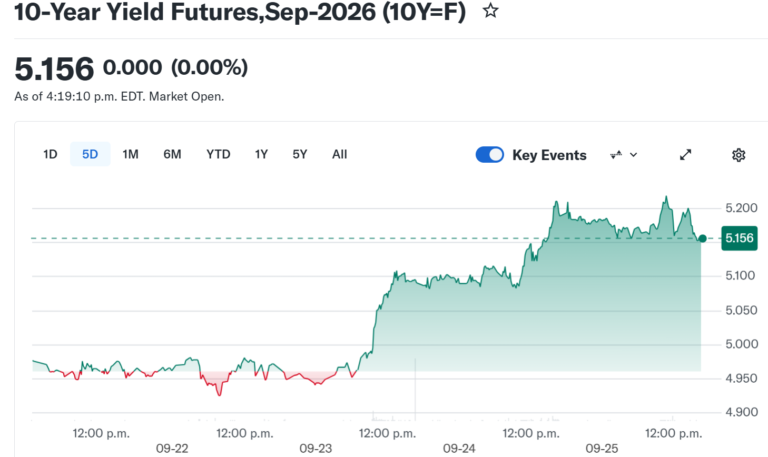
As trading moved into the second half of the week, market attention gradually shifted toward interest rates and energy prices. The U.S. 10-year Treasury yield rose from approximately 5.00% at the previous Friday’s close to around 5.18% on September 25, while the 30-year Treasury yield also remained elevated. Meanwhile, ongoing developments in the Middle East continued to influence oil prices, while gold and silver pulled back against a stronger U.S. dollar and higher Treasury yields.
Although the Canadian equity market experienced noticeable volatility during the middle of the week, it ended the week broadly unchanged. Overall, the week was characterized by strength in AI and semiconductor stocks, rising long-term interest rates, and continued volatility across commodity markets.
Last Week’s Key Economic Data & News Recap
U.S.-China Leadership Meeting and Trade Negotiations
On September 24, U.S. President Donald Trump and Chinese President Xi Jinping met at the White House, with trade relations, artificial intelligence, and other geopolitical issues among the key areas of attention. The meeting took place against the backdrop of ongoing discussions between the United States and China over trade and technology restrictions. Investors were particularly focused on whether the two sides could provide greater stability to existing trade arrangements. As of the September 25 close, markets were still awaiting more specific details from the U.S. administration regarding the negotiations. As a result, trading this week largely reflected investors’ assessment of the meeting and its potential follow-up, rather than a fully defined long-term change in trade policy. Reuters also identified the Trump-Xi meeting, along with AI, trade, Taiwan, and developments in the Middle East, as important market considerations in its September 24 coverage.
Meta Muse and Meta Connect Keep the AI Theme in Focus
Meta was one of the most closely watched companies in the AI sector this week. Meta launched its personal AI agent, Muse, on September 8, and investors increasingly focused on its early user data this week. Approximately two weeks after launch, Muse had reached around 2.8 million downloads and had surpassed ChatGPT in the free-app rankings on Apple’s App Store and Google Play in the United States and Canada. Meta shares rose 11.4% on September 21, bringing their gain since the launch of Muse to more than 20%, as investors reassessed the potential commercial opportunities associated with AI agents.
At the September 23 Meta Connect event, the company further outlined Muse’s development roadmap. Mark Zuckerberg demonstrated the integration of Muse with Meta AI glasses and introduced Muse Charm, which allows users to access Muse directly through hardware, while also expanding connections with retail, travel, and workplace software platforms. By September 25, Meta shares had recorded their fifth consecutive weekly gain, rising approximately 13% for the week, highlighting continued market attention toward the company’s AI products and hardware strategy.
AI and Semiconductor Stocks Continue to Lead
The strong investment interest in artificial intelligence continued to spread across the semiconductor supply chain this week. On September 21, the Philadelphia Semiconductor Index rose 4.3%, while AMD gained approximately 10%, Intel rose approximately 12%, and Arm Holdings increased approximately 17%. AMD’s market capitalization also surpassed US$1 trillion for the first time.
The strength in semiconductors was not limited to Monday. From September 18 to September 25, the SOX Index gained approximately 6.3% overall, despite brief pullbacks on September 23 and 24. Overall, investors continued to focus on AI-related chip demand and the potential support for the semiconductor industry from data-center infrastructure investment.
U.S. Treasury Yields Rise to Multi-Year Highs
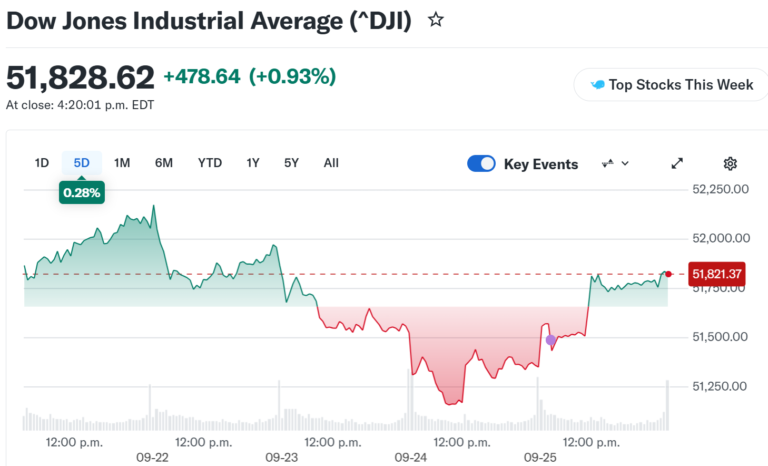
The U.S. Treasury market weakened noticeably in the second half of the week. On September 21, the 10-year Treasury yield briefly fell below 5%, providing a relatively supportive interest-rate environment for equities during the early part of the week. However, as U.S. economic data remained strong, oil prices moved higher again, and expectations for further Federal Reserve rate hikes increased, the 10-year Treasury yield moved back above 5% on Wednesday and continued rising to approximately 5.18% on Thursday. Long-term Treasury yields also remained at multi-year highs. The repricing of expectations for the future interest-rate path became an important factor weighing on equity valuations during the latter part of the week.
Investing with an AimStar's investment professional
Want expert advice at every step of your investing journey?
AimStar’s investment professionals can set you on the right course – and they can meet in-person or online.

Market Performance Review – Last Week
Source: Yahoo Finance
Canadian Equities:
S&P/TSX Composite
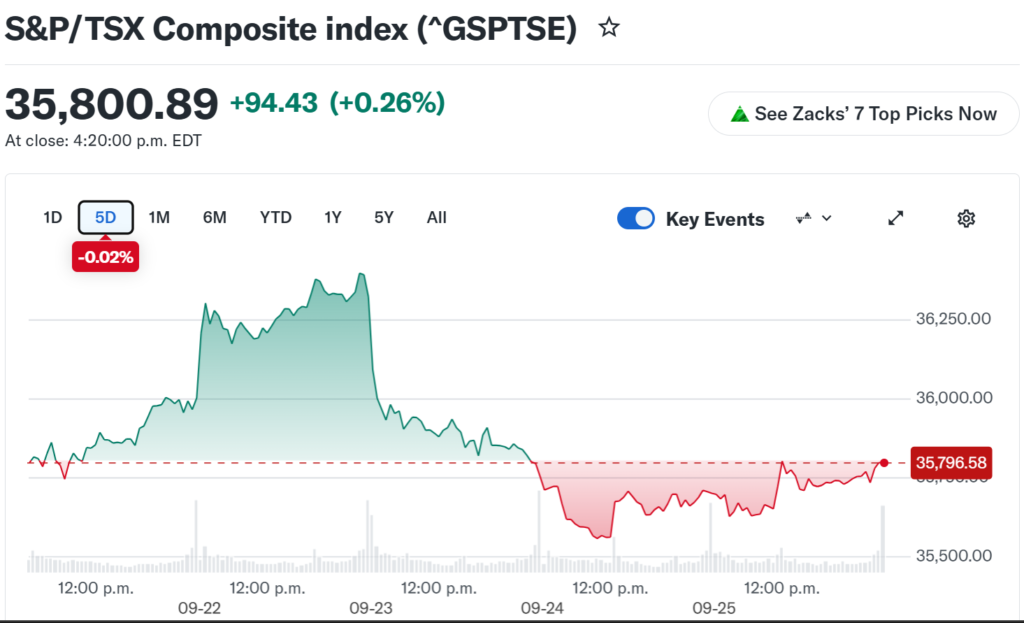
The Canadian equity market was broadly flat for the week, with the S&P/TSX Composite closing at 35,800.89, down approximately 0.02%. Against a backdrop of global market volatility, changes in commodity prices, and higher interest rates, Canadian equities remained relatively stable overall.
Source: Yahoo Finance
U.S. Equities:
S&P 500
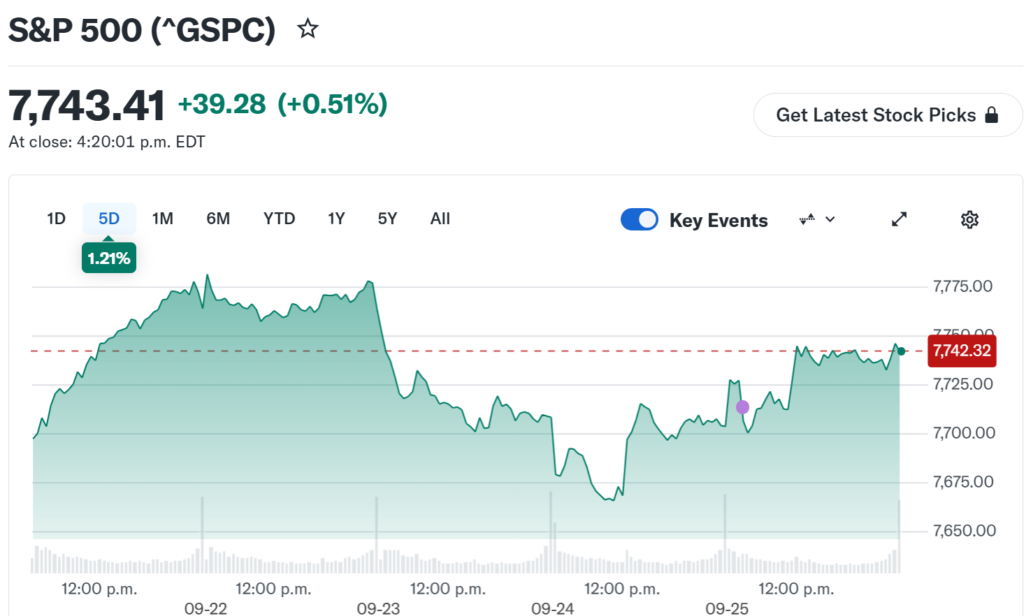
The S&P 500 gained approximately 1.21% for the week, supported by continued strength in technology and AI-related stocks. Despite the significant rise in long-term U.S. Treasury yields, major U.S. equity indexes remained at relatively elevated levels.
Dow Jones Industrial Average
The Dow Jones Industrial Average gained approximately 0.28% for the week, delivering a more moderate performance. The relatively stronger performance of technology and growth-oriented stocks contributed to the divergence between the major U.S. equity indexes.
Nasdaq Composite
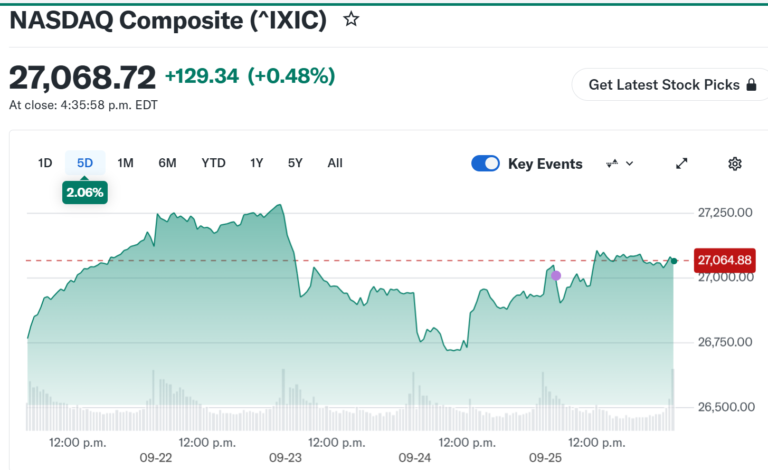
The Nasdaq Composite rose approximately 2.06% for the week, outperforming the other major U.S. equity indexes. Continued strength in semiconductor and technology stocks, along with sustained investor interest in AI-related investments, provided an important backdrop for the sector’s performance.
Source: Yahoo Finance
U.S. Bonds:
The U.S. 10-year Treasury yield rose significantly over the week, closing at approximately 5.18% on September 25. Higher long-term interest rates remained an important market variable, influencing equity valuations and broader financial conditions.
Source: Yahoo Finance
Forex Market:
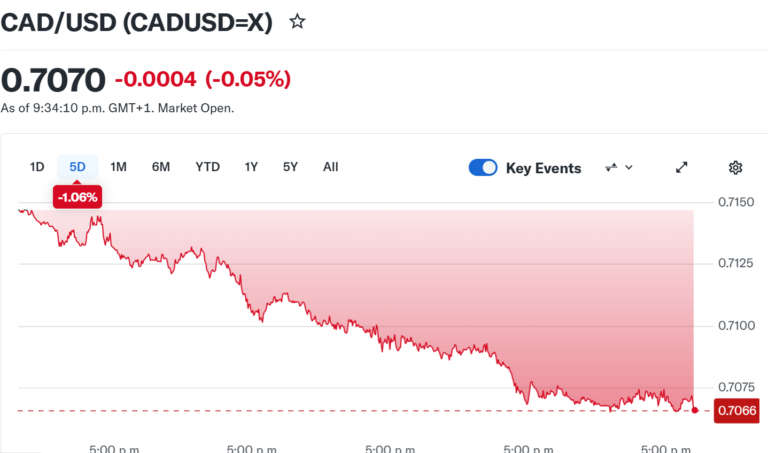
The Canadian dollar weakened overall during the week, declining against the U.S. dollar compared with the previous week. Interest-rate expectations, commodity prices, and broader movements in the U.S. dollar continued to influence the Canadian dollar.
Source: Yahoo Finance
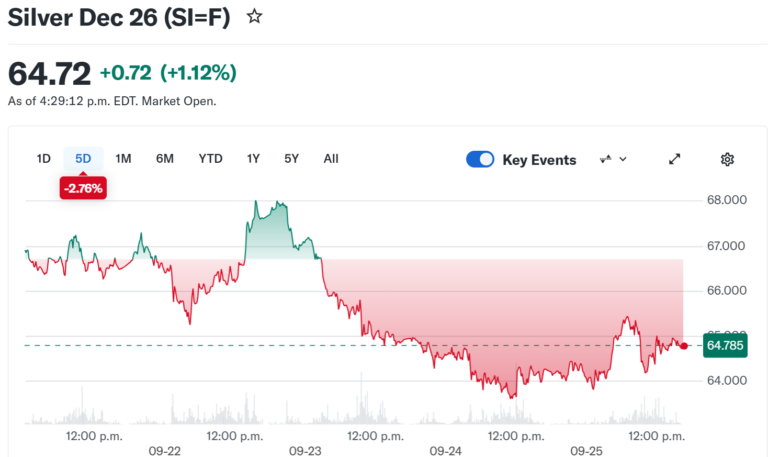
Gold & Silver Market:
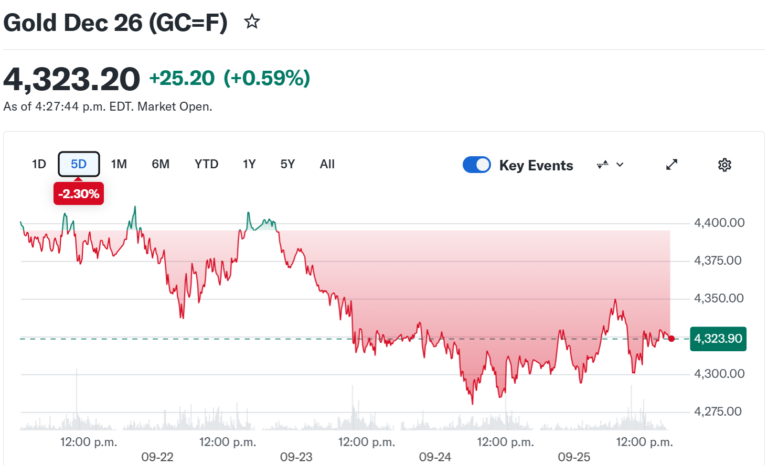
Gold futures declined approximately 2.3% for the week. As long-term U.S. Treasury yields moved higher, elevated bond yields placed some pressure on the non-yielding precious metal.
Silver futures also declined during the week, falling approximately 2.76% and underperforming gold. Precious metals broadly remained under pressure from higher U.S. interest rates and movements in the U.S. dollar.
Source: Yahoo Finance
Oil Market:
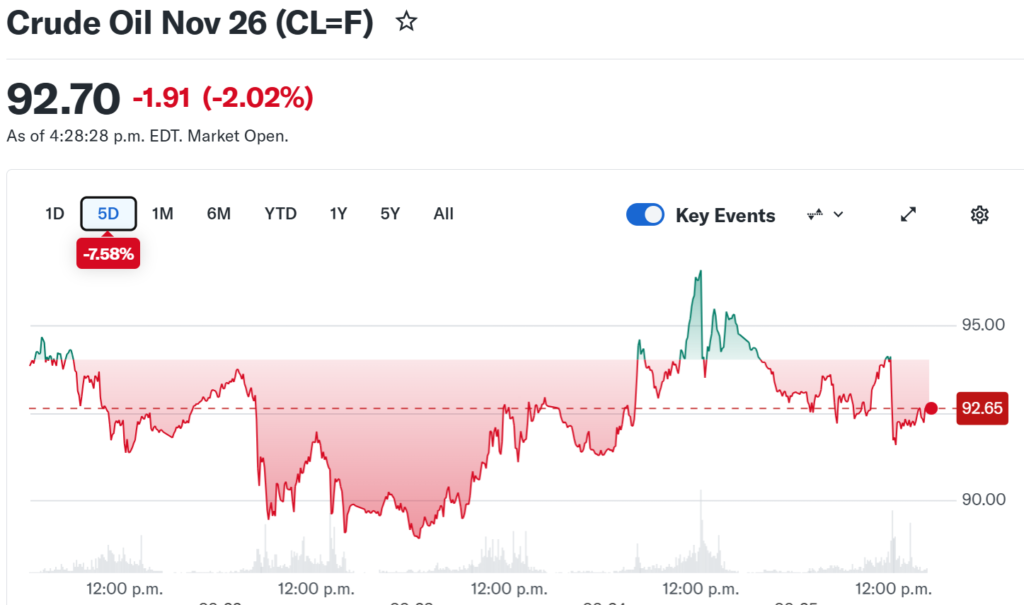
WTI crude oil futures declined significantly over the week, falling approximately 7.58% to close at around US$92.41 per barrel. The decline in oil prices eased some of the inflationary pressure previously driven by higher energy costs, while the energy market remained influenced by global economic growth expectations and geopolitical developments.
- Let us contact you
Investing with an AimStar's investment professional
Want expert advice at every step of your investing journey?
AimStar’s investment professionals can set you on the right course – and they can meet in-person or online.
Financial Market Data Copyright © 2026 AimStar myportfolio. Data as of September 28th, 2026, 15:30 PM EST

WHAT'S HAPPENING THIS WEEK
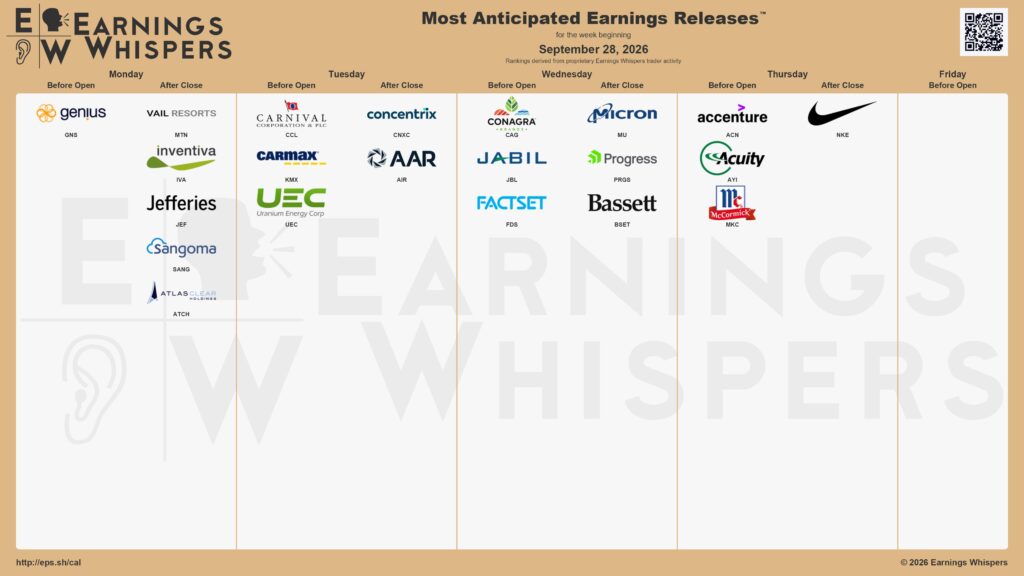
Upcoming Events This Week
September 28 (Monday)
- Economic Data & Events: U.S. Dallas Fed Manufacturing Index (September).
- Key Earnings: Vail Resorts, Jefferies, Inventiva, Sangoma Technologies, AtlasClear Holdings.
September 29 (Tuesday)
- Economic Data & Events: U.S. JOLTS Job Openings (August), Consumer Confidence Index (September); Bank of Canada Deputy Governor Toni Gravelle participates in a fireside chat at the Bloomberg Canadian Finance Conference.
- Key Earnings: Carnival, CarMax, Uranium Energy, Concentrix, AAR.
September 30 (Wednesday)
- Economic Data & Events: U.S. ADP Employment Report (September), third estimate of Q2 GDP, Personal Income and Spending (August), and PCE Price Index (August).
- Key Earnings: Conagra Brands, Jabil, FactSet Research Systems, Micron Technology, Progress Software, Bassett Furniture.
October 1 (Thursday)
- Economic Data & Events: U.S. ISM Manufacturing PMI (September), U.S. Initial Jobless Claims; Bank of Canada Senior Deputy Governor Carolyn Rogers delivers a speech.
- Key Earnings: Accenture, Acuity, McCormick, Nike.
October 2 (Friday)
- Economic Data & Events: U.S. Nonfarm Payrolls (September), Unemployment Rate (September), and Average Hourly Earnings (September). The U.S. Bureau of Labor Statistics is scheduled to release the employment report that day.
Author by: Sarah San
Edited & Published by: Sarah San
September 28th , 2026 15:30 PM EST. 10 min read

AimStar Capital Group Inc. is a Canadian full-service Investment Dealer, regulated by Canadian Investment Regulatory Organization (CIRO) and a member of Canadian Investor Protection Fund (CIPF). As an independent firm, AimStar is built on a foundation of innovation, integrity, and client-centricity. They are committed to providing unbiased advice and dedicated to the client’s needs, helping them achieve their financial goals.
AimStar is recognized as a Wealth Professionals 5-star Wealth Management Firm for 2024, this award recognized AimStar has offered exceptional client experience, a proven investment track record, continuous innovation, and stringent regulatory compliance.