
Key Focus This Week:
This Week’s Focus: Fed Policy Path, Global PMI and Canadian Consumer Spending
The focus of global markets is shifting from the Federal Reserve’s latest rate decision toward the future path of monetary policy. After raising the federal funds target range by 25 basis points to 3.75%–4.00% on September 16, investors will be watching upcoming comments from Fed officials for further clues on inflation, economic growth and the outlook for interest rates.
Global PMI data will also be in focus this week. September Flash PMI readings, due on September 23, will provide an updated assessment of manufacturing and services activity across major economies. With global economic activity remaining in expansion territory in August, the September data will offer further insight into the resilience of the global economy and could influence expectations for monetary policy and risk assets.
In Canada, July retail sales data will be released on September 24. With households continuing to face elevated borrowing costs and cost-of-living pressures, consumer spending will provide an important indication of domestic demand and economic momentum. The data may also influence expectations for the Bank of Canada, the Canadian dollar and Canadian bond yields.
Global central-bank decisions will remain another area of focus. The Swiss National Bank, Riksbank and Norges Bank are scheduled to announce their latest policy decisions on September 24, as investors assess how policymakers are balancing inflation risks with slowing economic growth.
In China, the latest Loan Prime Rate (LPR) will be announced on September 21. The market generally expects the 1-year and 5-year-plus LPRs to remain unchanged at 3.00% and 3.50%, respectively. Future policy signals and credit demand will remain important indicators for the outlook for Chinese economic growth.
Last Week’s Key Economic Data & News Recap
U.S. Inflation and the Federal Reserve
U.S. core CPI increased 0.3% month over month in August, above market expectations, contributing to a repricing of expectations for Federal Reserve policy.
The Fed subsequently raised the federal funds target range by 25 basis points to 3.75%–4.00% on September 16, marking its first rate hike since July 2023. The latest policy projections also suggested that further tightening could remain on the table before year-end.
At the same time, concerns over inflation, oil prices and the supply of U.S. government debt pushed the 10-year Treasury yield above 5% during the week, highlighting continued pressure on long-term borrowing costs.
Energy prices remained an important driver of global market sentiment.
Supply concerns related to an attack on Saudi Arabia’s east-west oil pipeline, as well as risks surrounding the Red Sea and Strait of Hormuz, temporarily heightened concerns over potential disruptions to global oil supplies and pushed international crude prices above US$100 per barrel.
Later in the week, reports of potential short-term ceasefire discussions between Saudi Arabia and the Houthi movement helped ease some supply concerns, leading to a pullback in Brent crude. However, developments in the Middle East remain an important source of uncertainty for the global energy and inflation outlook.
Major central banks continued to maintain a relatively restrictive policy stance.
The Bank of England held its policy rate at 3.75%, although three of nine policymakers supported an increase to 4.00%.
The Bank of Japan also raised its policy rate to approximately 1.25% on September 18, further tightening monetary conditions.
With energy prices remaining elevated and inflationary pressures persisting, the global interest-rate environment remains relatively restrictive.
AI and semiconductor-related sectors remained important themes in equity markets.
On September 18, Chinese technology stocks, particularly those related to semiconductors, advanced packaging, memory and computing chips, rallied strongly. The Shanghai Composite Index moved back above 3,900, while both the ChiNext Index and STAR 50 Index gained more than 2%.
The renewed strength in technology and growth-oriented sectors provided additional support to equity-market sentiment.
Investing with an AimStar's investment professional
Want expert advice at every step of your investing journey?
AimStar’s investment professionals can set you on the right course – and they can meet in-person or online.

Market Performance Review – Last Week
Source: Yahoo Finance
Canadian Equities:
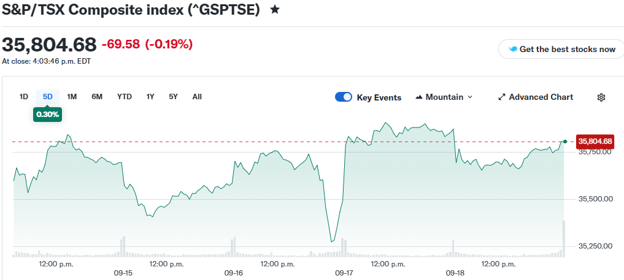
S&P/TSX Composite Index (^GSPTSE)
The Canadian equity market moved lower early in the week before recovering strongly. The S&P/TSX Composite Index reached a weekly high of approximately 35,920 during the second half of the week.
The index closed at 35,804.68 on September 18, gaining approximately 0.30% for the week. Overall, the TSX remained in a relatively high-level consolidation range.
Source: Yahoo Finance
U.S. Equities:
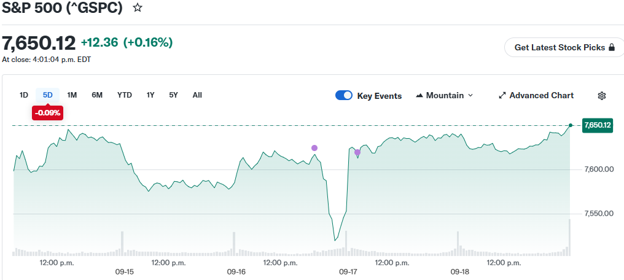
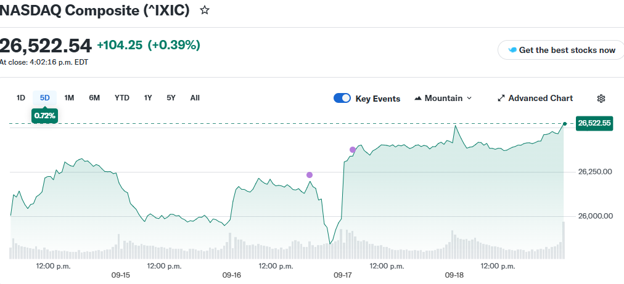
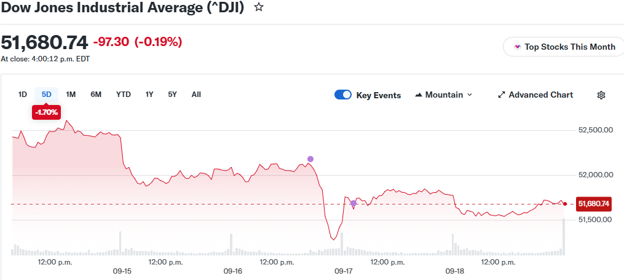
U.S. equities were mixed during the week, with technology stocks outperforming.
The S&P 500 closed at 7,650.12, down approximately 0.09%.
The Nasdaq Composite closed at 26,522.54, gaining approximately 0.72%.
The Dow Jones Industrial Average closed at 51,680.74, declining approximately 1.70%.
The divergence reflected continued strength in technology-related stocks, while more economically sensitive areas of the market faced greater pressure from elevated interest rates.
Source: Yahoo Finance
U.S. Bonds:
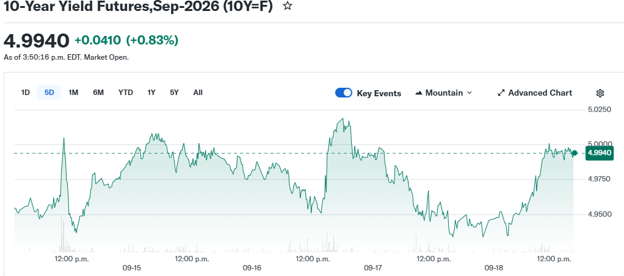
The U.S. 10-year Treasury yield remained elevated and volatile throughout the week.
The yield moved above 5.00% early in the week, reaching approximately 5.02%, before falling toward 4.94% and subsequently moving higher again.
As of September 18, the 10-year Treasury yield stood at approximately 4.994%, reflecting continued elevated expectations for interest rates and long-term borrowing costs.
Source: Yahoo Finance
Forex Market:
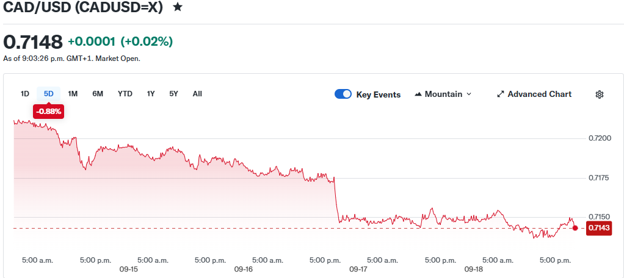
The Canadian dollar weakened against the U.S. dollar during the week.
CAD/USD initially traded above 0.7200 before declining steadily. As of September 18, the exchange rate stood at 0.7148, representing a weekly decline of approximately 0.88%.
Although the Canadian dollar recovered slightly toward the end of the week, it remained near the lower end of its weekly range.
Source: Yahoo Finance
Gold & Silver Market:
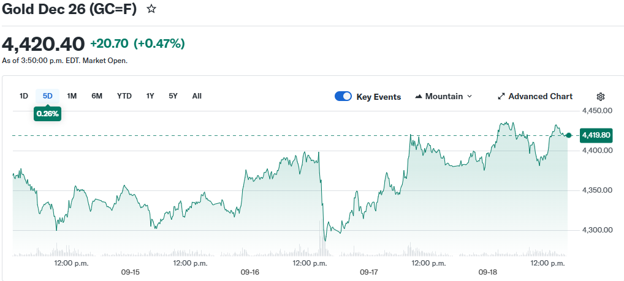
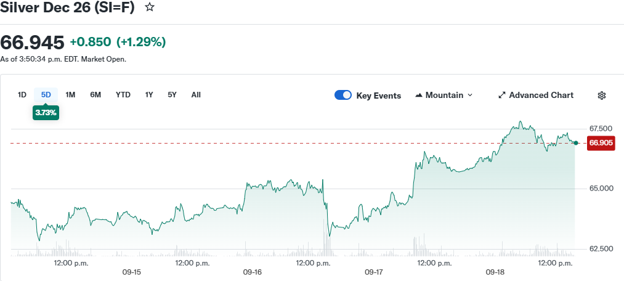
Precious metals remained broadly firm.
December gold futures closed at US$4,420.40 per ounce, gaining approximately 0.26%.
December silver futures closed at US$66.945 per ounce, gaining approximately 3.73%.
Silver outperformed gold during the week, while the broader precious-metals complex remained supported by continued uncertainty surrounding inflation, monetary policy and global markets.
Source: Yahoo Finance
Oil Market:
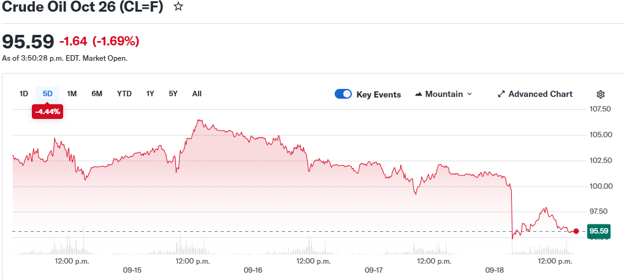
WTI crude experienced a notable rise followed by a sharp reversal.
October 2026 WTI futures initially climbed to approximately US$106.75 per barrel before moving lower, with the decline accelerating during the second half of the week.
WTI closed at US$95.59 per barrel on September 18, down approximately 4.44% for the week.
- Let us contact you
Investing with an AimStar's investment professional
Want expert advice at every step of your investing journey?
AimStar’s investment professionals can set you on the right course – and they can meet in-person or online.
Financial Market Data Copyright © 2026 AimStar myportfolio. Data as of September 21st, 2026, 15:30 PM EST

WHAT'S HAPPENING THIS WEEK
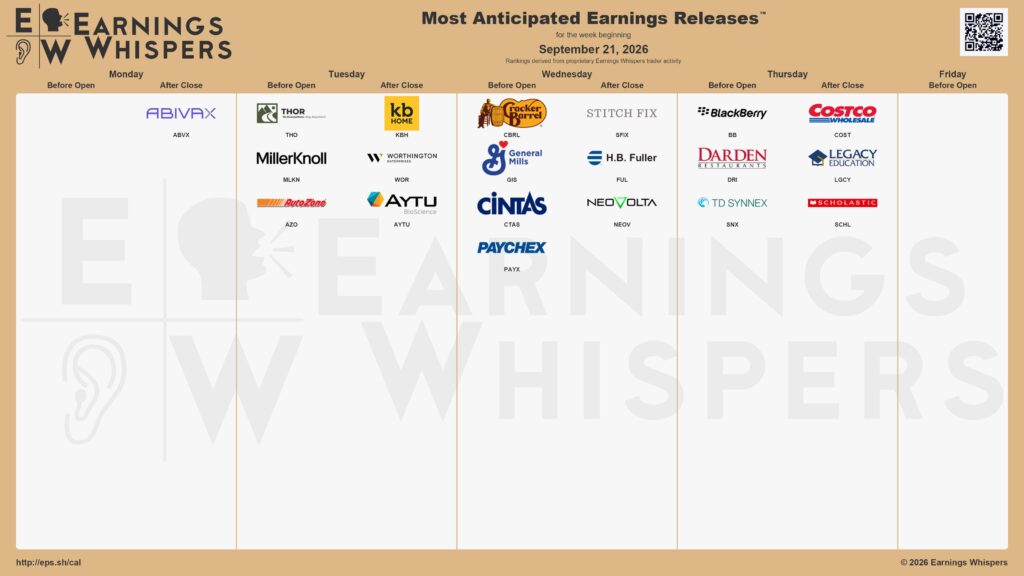
Upcoming Events This Week
September 21 (Monday)
Economic Data & Events: China 1-year and 5-year-plus Loan Prime Rates (LPR); U.S. August Chicago Fed National Activity Index; Bank of Canada Governor Tiff Macklem speaking in Halifax.
September 22 (Tuesday)
Economic Data & Events: U.S. September Richmond Fed Manufacturing Index; Federal Reserve Vice Chair Philip Jefferson speaking at the U.S. Treasury Market Conference.
Key Earnings: AutoZone, KB Home, Thor Industries, MillerKnoll, Worthington Enterprises.
September 23 (Wednesday)
Economic Data & Events: U.S., Eurozone and U.K. September Flash Manufacturing and Services PMIs; Federal Reserve Governor Michael Barr speaking at a public event.
Key Earnings: Cintas, General Mills, Paychex, H.B. Fuller, TD SYNNEX, Cracker Barrel.
September 24 (Thursday)
Economic Data & Events: Canada July retail sales; U.S. August new home sales; U.S. weekly initial jobless claims; Swiss National Bank, Riksbank and Norges Bank interest rate decisions.
Global Events: U.S. President Donald Trump and Chinese President Xi Jinping scheduled to meet in Washington, with trade, tariffs, technology and broader geopolitical issues among the key areas of focus.
Key Earnings: Costco Wholesale, BlackBerry, Darden Restaurants, TD SYNNEX.
September 25 (Friday)
Economic Data & Events: U.S. August preliminary durable goods orders; September final University of Michigan Consumer Sentiment.
Author by: Sarah San
Edited & Published by: Sarah San
September 21st , 2026 15:30 PM EST. 10 min read

AimStar Capital Group Inc. is a Canadian full-service Investment Dealer, regulated by Canadian Investment Regulatory Organization (CIRO) and a member of Canadian Investor Protection Fund (CIPF). As an independent firm, AimStar is built on a foundation of innovation, integrity, and client-centricity. They are committed to providing unbiased advice and dedicated to the client’s needs, helping them achieve their financial goals.
AimStar is recognized as a Wealth Professionals 5-star Wealth Management Firm for 2024, this award recognized AimStar has offered exceptional client experience, a proven investment track record, continuous innovation, and stringent regulatory compliance.